
Fixed term ending? Check more than the new rate
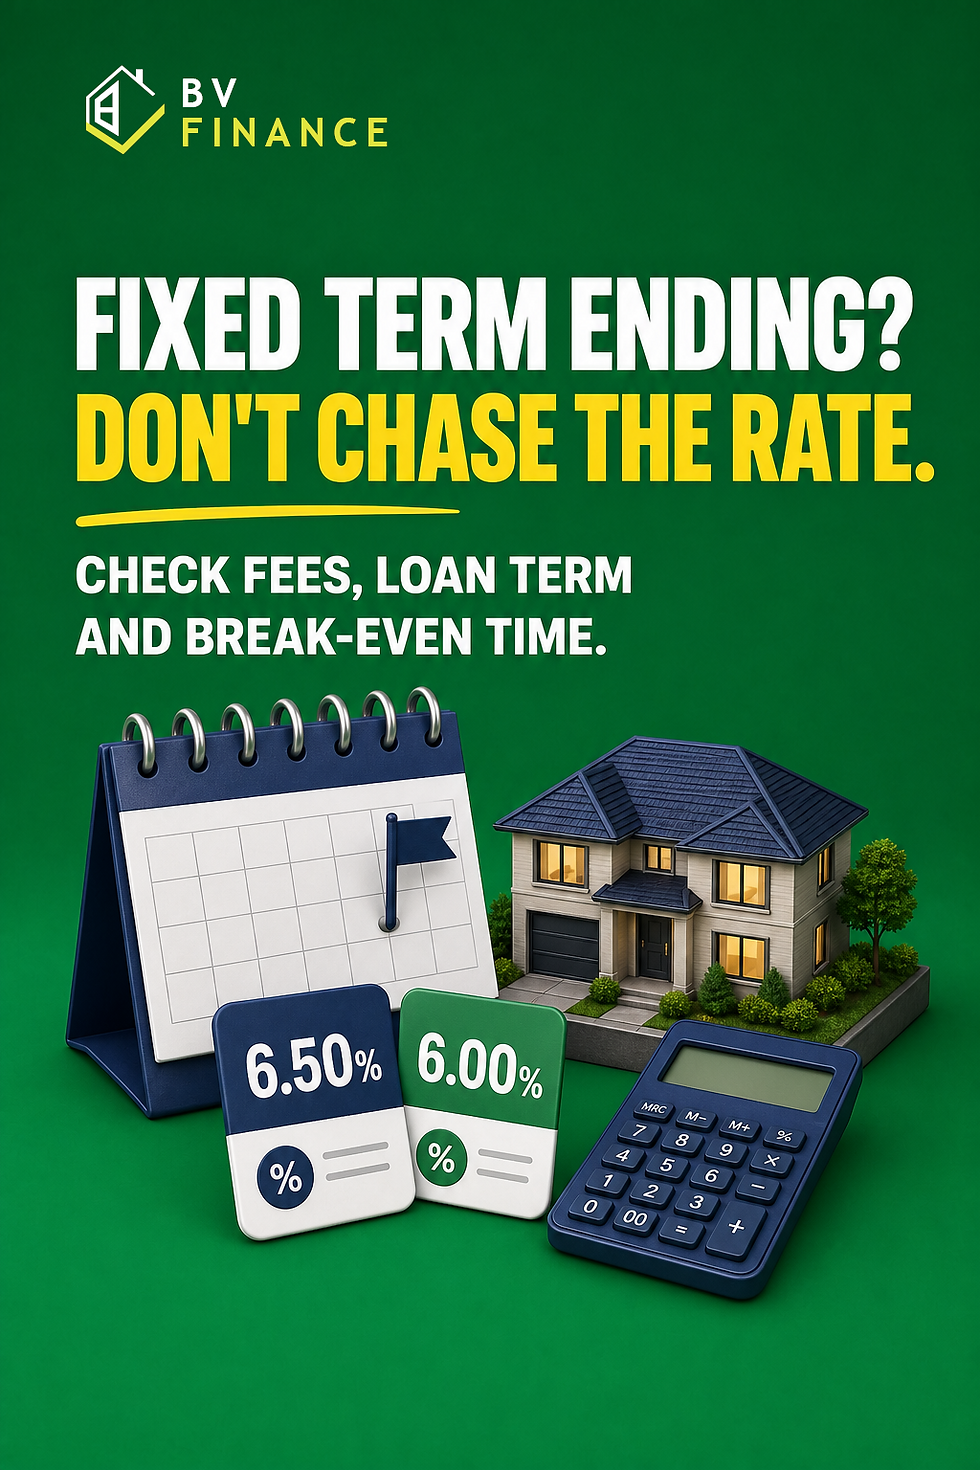
When a fixed-rate period is ending, a lower advertised rate can look like the obvious next move. But a smaller repayment does not automatically make switching worthwhile. The fees, remaining loan term and time needed to recover the costs all affect the result.
Moneysmart advises borrowers to compare the benefits of a lower rate with fixed-rate break fees, discharge fees, application fees and other switching costs. It also warns against extending the loan beyond the years remaining on the current mortgage without considering the extra interest.
Illustrative example: calculate the break-even time

Balance and term — $600,000 with 20 years remaining, principal and interest repayments.
At 6.50% — the monthly repayment is approximately $4,473.
At 6.00% — the monthly repayment is approximately $4,299, about $175 less per month.
Cost recovery — if total switching costs are $3,000, the repayment difference alone takes about 17 months to recover those costs.
This is an educational illustration only. It excludes product-specific fees, offset balances, package pricing, lender assessment and future rate changes.
Four checks before switching

1. Fixed-period status — confirm whether the fixed period has ended and whether a break fee applies today.
2. Total switching costs — add discharge, application, internal switching, valuation and any other relevant charges.
3. Remaining loan term — compare the new term with the years left on the current loan, not with a fresh 30-year starting point.
4. Break-even time — calculate how long the expected savings take to recover the upfront costs.
Bottom line
Compare total cost and break-even time before choosing to stay with the current lender, switch products internally or refinance elsewhere. A lower rate is useful only when the overall structure also suits your plans.
Sources
Moneysmart — Switching home loans
Moneysmart — Pay off your mortgage faster
General information only. This is not financial advice. Loan options and eligibility depend on your personal income, liabilities, assets and lender assessment criteria.


Comments