
Deposit saved. Is your cash ready?
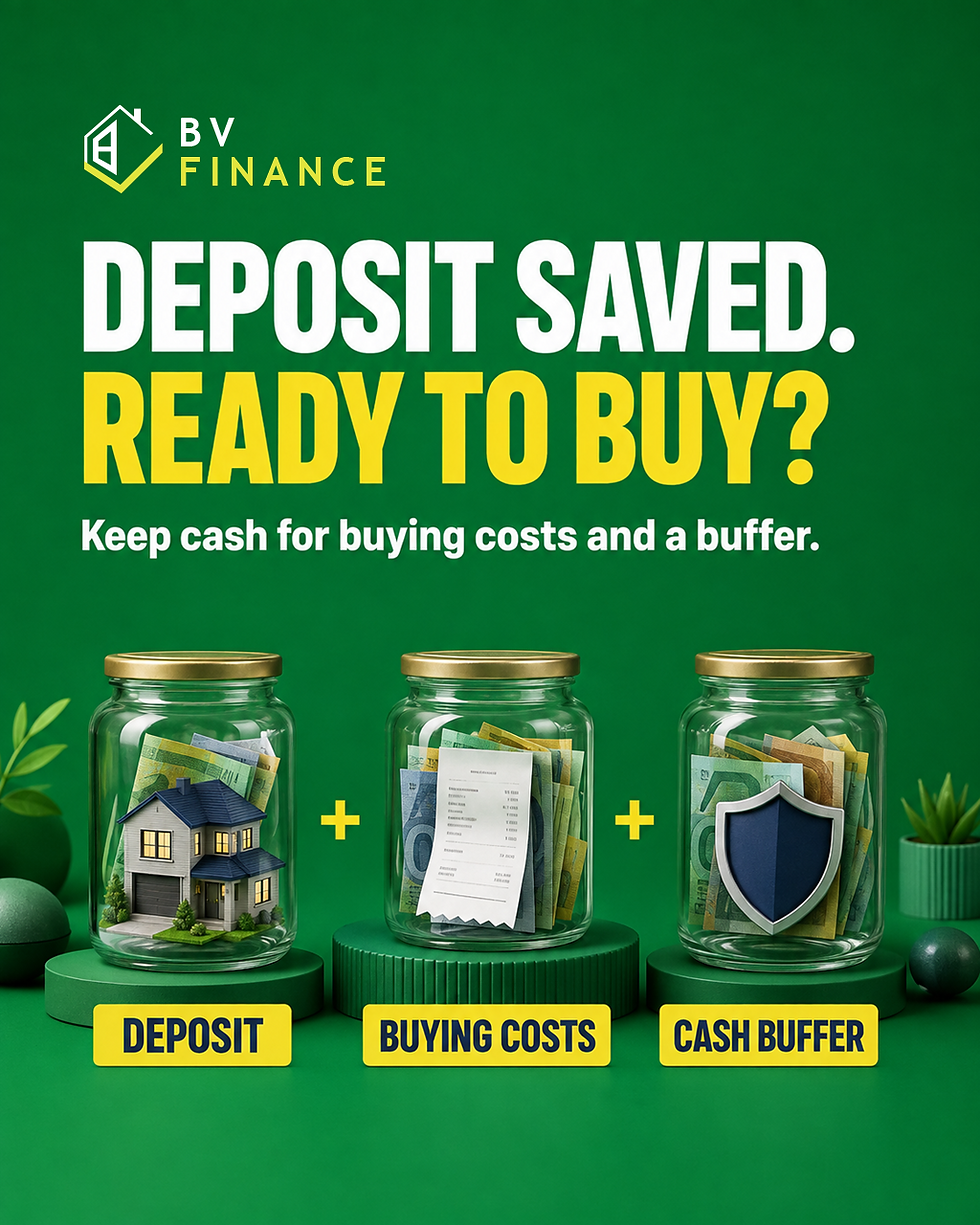
Saving a deposit does not mean every dollar of savings is available for the deposit. A buyer may also need cash for transfer duty, legal or conveyancing work, property reports, loan fees, moving and costs that arise after settlement.
Moneysmart, ASIC's Australian Government money guide, says a home-deposit savings goal should include buying costs as well as the deposit. It also explains that lenders assess more than the deposit, including income, expenses, debts, credit history and employment.
A $60,000 cash-allocation example

Illustration only: start with $60,000 of savings, set aside $10,000 for buying costs and $5,000 as a cash buffer. That leaves $45,000 available for the deposit: $60,000 − $10,000 − $5,000 = $45,000.
The amounts are not a fee quote, a lender requirement or a recommended buffer. Actual duty, concessions, legal costs, inspections, lender charges and household needs vary by property, location and personal circumstances.
Three checks before making an offer

1. Confirm buying costs — ask the relevant providers when each cost is payable. In NSW, the Government lists transfer duty, property reports, legal or conveyancing fees, registration charges and loan-application costs among possible upfront items; other states and territories have their own rules.
2. Keep a cash buffer — allow for urgent or unexpected household costs without assuming one amount suits everyone. Moneysmart recommends working from your own expenses when setting an emergency-fund goal.
3. Check borrowing capacity — savings alone do not guarantee loan approval. The lender still assesses whether the proposed loan is affordable under its current criteria.
Keep the legal and finance checks separate
A conveyancer or solicitor can explain the contract, transfer process and legal responsibilities. BV Finance can help you compare the deposit, buying costs, buffer and proposed borrowing so the purchase budget is tested before you commit.
Sources and practical tools
General information only. This is not financial advice. Loan options and eligibility depend on your personal income, liabilities, assets and lender assessment criteria.


Comments