
Is a 5% deposit all the cash you need?
The Australian Government 5% Deposit Scheme may allow an eligible first-home buyer to purchase with a minimum 5% deposit and without paying Lenders Mortgage Insurance. That lowers one hurdle, but it does not mean 5% is the buyer's complete cash requirement or that the home loan has already been approved.
The Scheme still has eligibility requirements. Buyers must meet the applicable property price cap, use a Participating Lender and satisfy that lender's credit policy and loan-approval criteria. The lender still assesses income, liabilities, expenses, employment and credit information.
What does the official Scheme information mean?

A 5% deposit can open the first door for an eligible buyer. It does not replace lender assessment, cover every transaction cost or provide the household with money for expenses after settlement.
Property price caps and individual eligibility still apply. A buyer should confirm the Scheme rules and obtain a lender assessment before treating the lower minimum deposit as part of a workable purchasing plan.
Separate the three cash jobs
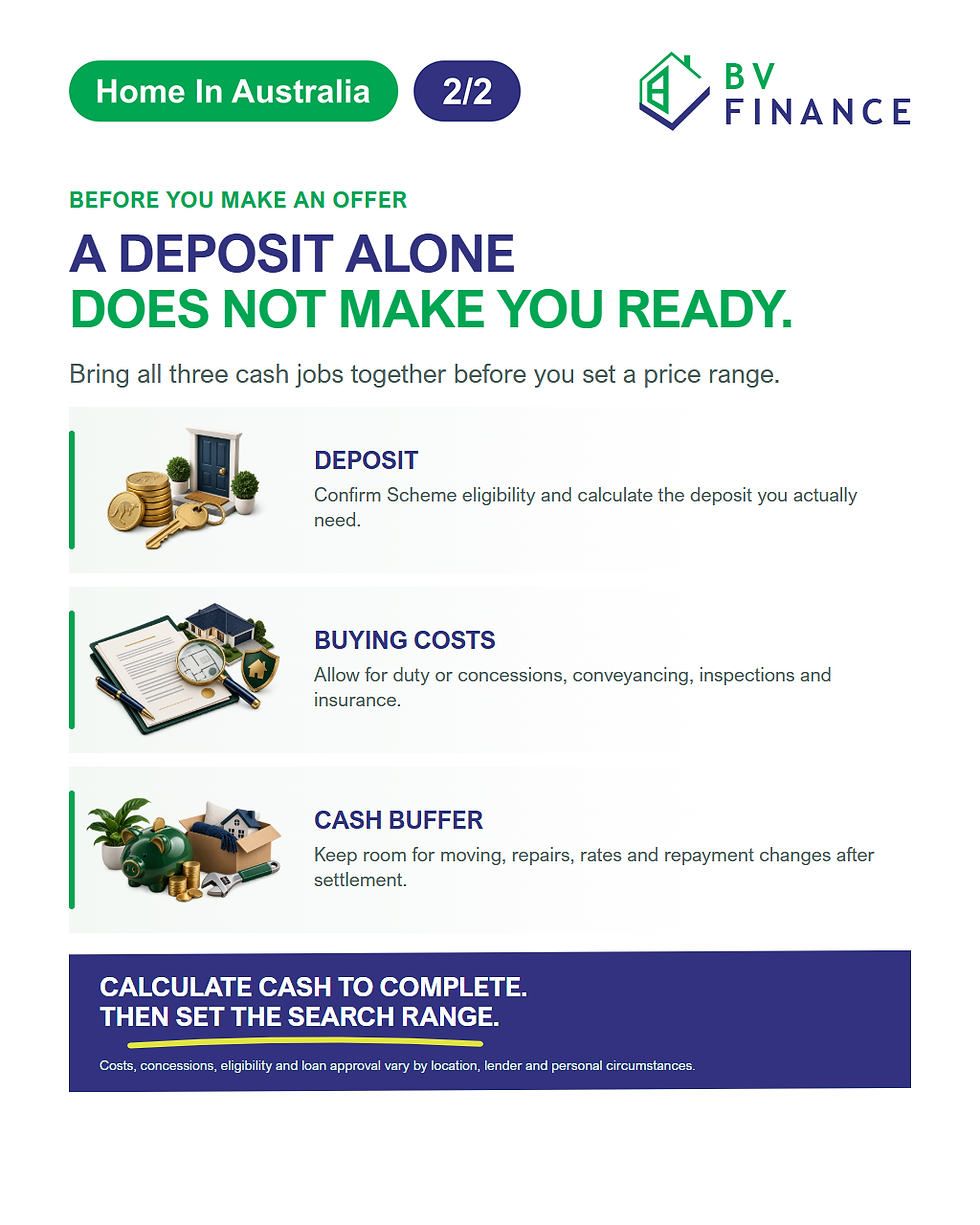
Deposit: confirm Scheme eligibility and calculate the amount required for the selected property. A minimum percentage is not a personalised approval or savings target.
Buying costs: allow separately for transfer duty or available concessions, conveyancing or legal work, building and pest inspections, insurance and other location-specific charges. These costs vary by state, property and personal circumstances.
Cash buffer: retain room for moving, immediate repairs, council rates or strata costs, bills and changes in repayments after settlement. Using every available dollar to complete the purchase can leave the household exposed to the first unexpected expense.
Calculate cash to complete before setting a search range
BV Finance can help compare eligible loan options and place the deposit, purchasing costs and expected repayments into one household cash-flow view. Scheme access, loan terms and final approval remain subject to the buyer, property and lender assessment.
Sources and practical tools
General information only. This is not financial advice. Loan options and eligibility depend on your personal income, liabilities, assets and lender assessment criteria.


Comments