
Offset savings: are they worth the extra fees and loan rate?


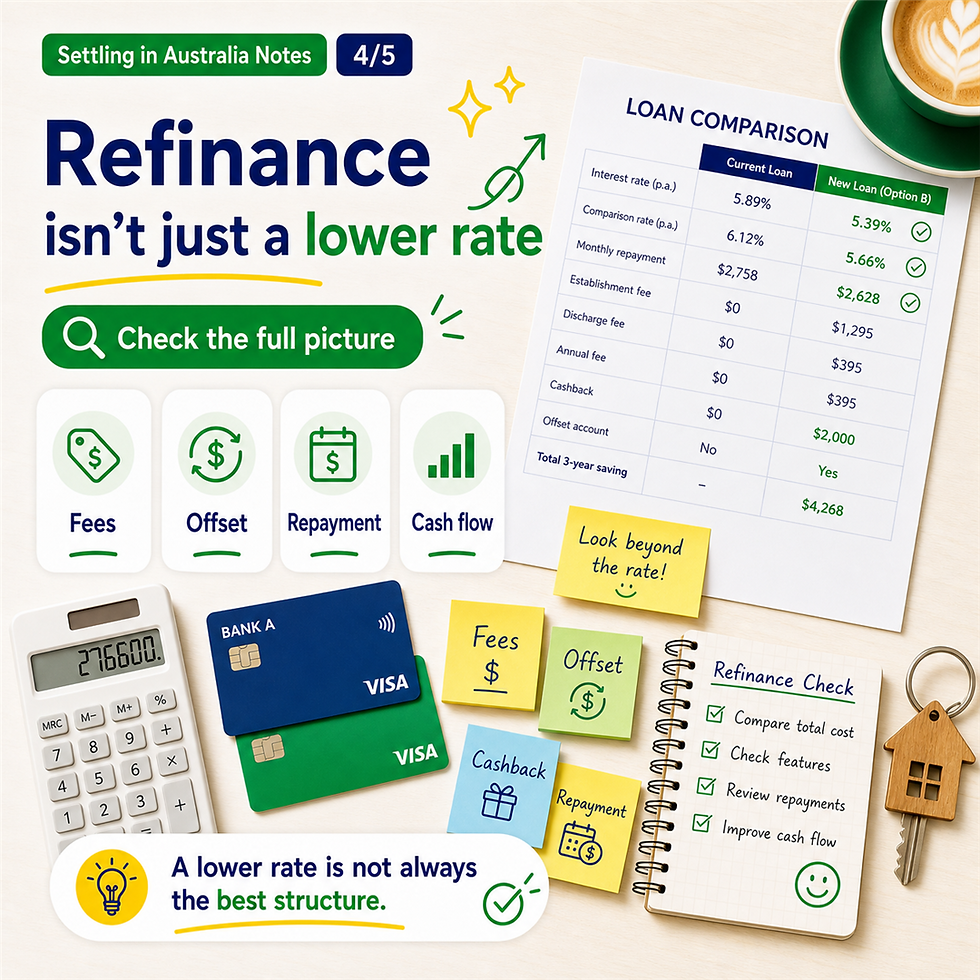
Not necessarily. Interest saved is only one side of the comparison. An offset-linked loan can cost more through fees or a higher rate, so compare the benefit after extra costs, not just the feature name.
The official cost warning

ASIC Moneysmart, checked on 13 October 2026, says offset features can carry higher interest rates, account fees, or both. It recommends comparing these costs with the interest you expect to save. This is general guidance, not a current product quote.
A worked example, not a product offer

Assume $10,000 remains in a correctly linked 100% offset every day for one full year, the home loan rate stays at 6%, and enough loan principal remains for the full balance to offset interest. Simplified interest avoided is $10,000 × 6% = approximately $600.
Now assume an extra annual fee of $395 compared with the alternative. $600 − $395 = approximately $205. The fee is hypothetical, not a verified lender charge. The $205 is a subtotal before any higher loan-rate cost, not the final net saving.
If the offset-eligible loan also has a higher rate, that additional cost can reduce or eliminate the subtotal. Request a like-for-like whole-loan comparison using the actual loan balance and terms. Daily balances, rates, charges and product conditions can change the result; this is not a savings guarantee.
Turn the example into a useful comparison
Bring a realistic picture of money left after bills, not only the balance on payday. Write down the two proposed loan rates and every additional annual, package or account fee. Keep loan amount, remaining term and repayment basis consistent, and include switching costs if refinancing.
Ask the lender to confirm the offset percentage and account linkage, then compare the whole arrangement. Do not add up separate benefits twice or treat the illustration as a personal recommendation.
Compare the structure with BV Finance
BV Finance can help organise a comparison of available loan structures using your balances, fees and financial commitments. Suitability and eligibility depend on your circumstances and lender assessment.
Sources and practical tools
General information only. This is not financial advice. Loan options and eligibility depend on your personal income, liabilities, assets and lender assessment criteria.


Comments